Plastics & Chemical Recycling
PlasticsToday Labels US PET Recycling a 'Crisis' as EPR Rules Take Hold
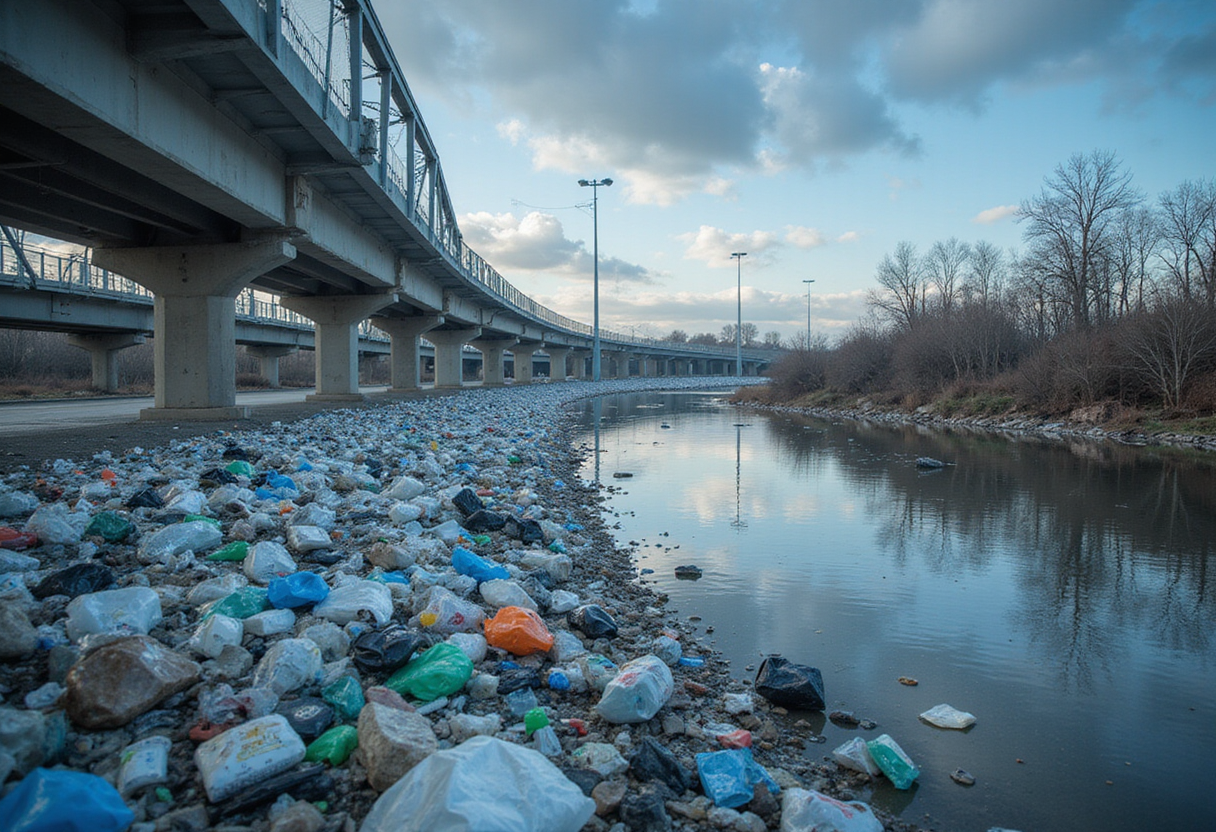
PlasticsToday has labeled strain on US PET recycling infrastructure a 'crisis,' framing pressure on MRFs, reclaimers, and rPET markets as state EPR laws take effect in 2025.
Waypoints
PlasticsToday this week labeled US PET recycling infrastructure a 'crisis' affecting collection, sorting and reclaim operations
NAPCOR reported a 60.5% US PET bottle recycling rate for 2022, the highest of any major plastic
Oregon's Recycling Modernization Act takes effect January 1, 2025 under a PRO structure
California's SB 54 sets producer reporting and PET recyclability targets running through 2032
Colorado, Minnesota, Maine and Washington have enacted packaging EPR laws with 2025-2027 implementation dates
US reclaimers collected enough polyethylene terephthalate (PET) bottles in 2022 to push the national recycling rate to 60.5%, the highest of any major plastic, according to the National Association for PET Container Resources (NAPCOR). PlasticsToday this week labeled the infrastructure underlying that figure a "crisis" facing collection, sorting and reclaim operations across the country.
The headline, distributed through Google News indexing of the trade publication's feed, does not name a single triggering event. The framing nevertheless captures pressures that buyers, sellers and municipal program operators have flagged throughout 2024 and 2025: weak offtake for mixed-color flake, contested bale specifications under Association of Plastic Recyclers (APR) guidance, rising Material Recovery Facility (MRF) operating costs, and ongoing consolidation among US reclaimer operators.
What is actually breaking in the PET loop?
PET is the most-recycled plastic in the US by volume. A handful of large reclaimers process the majority of curbside-collected bottles, and the reclaimer footprint has contracted in recent years as commodity margins compressed and California Redemption Value (CRV) program reforms reshaped material flows.
Built reclaimer capacity has not kept pace with the volume of bottles collected. When US reclaimers run at high utilization, surplus bales historically move to export channels — a pathway that narrowed sharply after China's National Sword policy and tightened further under EU waste shipment rules and country-of-origin requirements in Vietnam, Indonesia and Malaysia.
Where is the pressure showing up most?
Trade press coverage throughout 2024 and 2025 has highlighted three pressure points:
- MRF economics. Rising labor, trucking and energy costs have pushed many MRFs to renegotiate tipping fees, often passing costs back to the municipalities that fund curbside collection.
- Reclaimer concentration. Mid-sized reclaimers have closed or converted to other resins, concentrating processing in fewer large facilities and lengthening average haul distances for baled bottles.
- Recycled-content pellet markets. Virgin PET pricing tied to paraxylene and monoethylene glycol (MEG) feedstocks has compressed the green-premium spread, weakening offtake for food-grade rPET under state procurement rules.
What regulatory milestones are approaching?
The next 12 months carry a heavy state policy schedule:
- Oregon's Recycling Modernization Act takes effect January 1, 2025, shifting program costs to producers through a Producer Responsibility Organization (PRO) structure.
- California's SB 54 requires producer reporting and ramps up recycled-content and recyclability targets for PET packaging through 2032.
- Colorado, Minnesota, Maine, Washington and additional states have enacted Extended Producer Responsibility (EPR) packaging laws with implementation dates between 2025 and 2027.
- The US Federal Trade Commission's Green Guides revision, opened for comment in 2022, remains pending and will set baseline rules for "recyclable" claims on PET packaging.
The PlasticsToday headline lands against that policy timeline. The trade publication did not detail underlying data in the indexed version, but the framing matches what MRF operators and reclaimers have told the trade press for at least two quarters.
What happens next?
The next inflection point is the start of state EPR implementation in 2025. Oregon's PRO begins paying reimbursements to MRFs and local governments for PET collection, while California's CalRecycle begins enforcing SB 54 reporting on the producer side.
If those payments reach operators in time to offset the cost pressures flagged in the PlasticsToday piece, the "crisis" framing may prove a cyclical squeeze. If they arrive behind schedule — or below the level needed to sustain smaller MRFs — the next 12 months could bring additional curbside program dropouts and further reclaimer consolidation.
The data point to watch is the 2024 NAPCOR recycling rate, expected later in 2025, which will show whether the 60.5% headline figure held, slipped, or recovered under the pressures the trade publication has now elevated.
via Google News: Recycling industry (Source)
More from Daniel Okafor
Show full bio
Correspondent covering consumer brands and retail at Circular Wire.
285 articles